Source lineage from financial record to reviewed finding
Finsider Labs / Updated September 12, 2026 / 3 min read
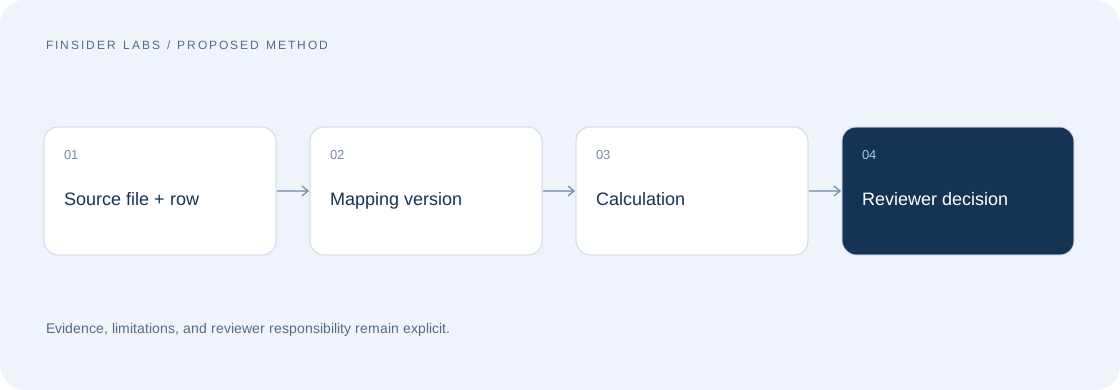
A financial finding becomes useful when another reviewer can reconstruct its source, calculation, assumptions, and decision.
Research question
Can another reviewer reconstruct a material finding using its retained inputs, transformations, and decision record? The proposed method treats reproducibility and professional approval as separate properties. Neither implies the other.
Record model
Represent source files and derived schedules as entities, imports and calculations as activities, and responsible people or software processes as agents. A row citation should include file identity and parser context; row numbers can change between exports. A hash detects a change in bytes but does not establish that a document is authentic or complete.
Transformation contract
Store the input reference, output identifier, mapping version, formula or calculation version, period, exclusions, and units. Corrections create a new version rather than silently rewriting the previous result. Keep access permissions around both source records and derived outputs; a valid link is not permission to disclose its contents.
Proposed reconstruction test
Give a second reviewer the output and authorized source package. Ask them to locate the source, reproduce the calculation, identify assumptions, and distinguish the approval state. Report source resolution, numerical agreement, and missing-context rates independently. Test renamed files, repeated imports, changed mappings, deleted source access, and partial evidence. No test results are claimed here.
Limitations
Lineage records can faithfully preserve an incorrect mapping or misleading input. Review still needs accounting context and source completeness. This is a proposed financial workflow informed by provenance concepts, not a claim that Finsider implements every W3C PROV relation or has passed a conformance assessment.
A minimal lineage record
Illustrative example / not empirical results
| Field | Illustrative value | Why retain it |
|---|---|---|
| Source reference | ledger.csv, row 42, retained file hash | Identify the input without relying on its display name |
| Transformation | Account map v3; period filter Jan-Dec | Explain which records entered the result |
| Derived output | Candidate ADJ-07 | Keep the candidate separate from reported books |
| Review event | Returned for supporting invoice | Preserve disagreement and unresolved evidence |
Sources and context
These sources inform the discussion. They do not validate Finsider product performance or the proposed method.
The provenance model distinguishes entities, activities, and responsible agents. The financial record design here is Finsider's proposed application, not a claim of PROV certification.