An evidence-first framework for pre-QoE screening
Finsider Labs / Updated September 12, 2026 / 3 min read
A first-pass financial screen should identify the next diligence questions, not turn incomplete records into definitive conclusions.
Research question
How should an initial financial screen distinguish a supported observation from a candidate interpretation and an unassessable check? The proposed unit of analysis is a target-company, analysis-period, check tuple. It is not a ranking of acquisition targets.
Input contract
Record the entity, currency, period, account coverage, file identity, and import version. Keep ledger exports separate from bank evidence and management explanations. Declare which inputs each check requires before executing it. A coverage matrix should distinguish absent files, unreadable files, partial periods, and usable evidence.
Procedure
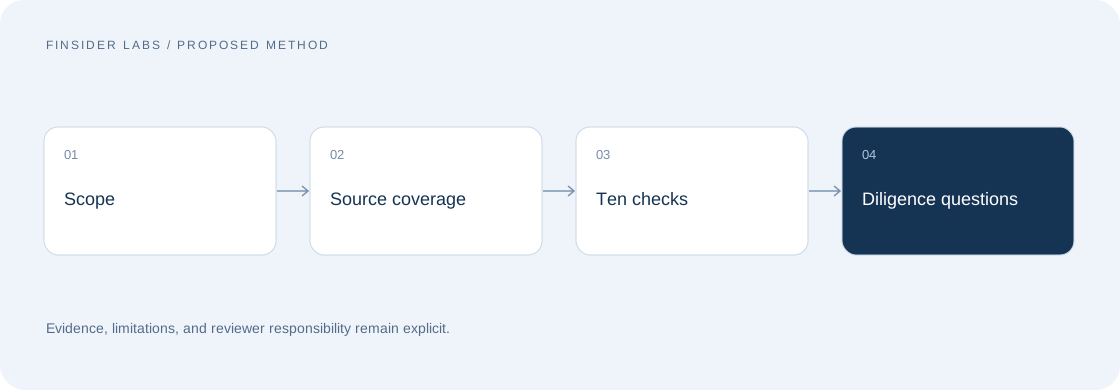
First reconcile the available financial baseline. Then run the applicable checks, retaining inputs and calculation logic. Assign each output a status: supported observation, candidate requiring review, or not assessable. Record a reason and next action for every candidate or gap. A screen may contain several statuses; do not collapse them into a single confidence score.
Proposed evaluation
Use an independently reviewed test set with declared source coverage and expected check eligibility. Measure eligibility agreement, source-location correctness, and unsupported-claim frequency separately. Report numerator and denominator for each rate. Include missing-period and duplicated-export cases. No dataset, sample size, model comparison, or measured results are published in this note.
Boundary of the method
A screen does not establish sustainable earnings, prove fraud, or replace a scoped QoE engagement. A not-assessable result is useful when it identifies the missing source. Reviewers remain responsible for context, materiality, and the decision to expand diligence.
An expense worth investigating, not an automatic addback
Illustrative example / not empirical results
| Observation | Evidence needed | Screening treatment |
|---|---|---|
| A ledger memo says "one-time consulting" | Invoice, service period, management explanation | Candidate only |
| Bank statements cover two of twelve months | Statements for the missing accounts and periods | Full-period cash check not assessable |
| Two rows share a description and amount | Transaction IDs and source export history | Potential duplicate; do not remove automatically |
Sources and context
These sources inform the discussion. They do not validate Finsider product performance or the proposed method.
Financial due diligence considers earnings, assets, working capital, and cash flow. This is industry context, not evidence about Finsider performance.
Earnings normalization requires analysis of historical results and proposed adjustments, not automatic acceptance of management addbacks.